Monday, July 30, 2018

5 Expenses Homeowners Pay That Renters Don't

Homeownership may be a goal for some, but it’s not the right fit for many.

Renters account for 37 percent of all households in America - or just over 43.7 million homes, up more than 6.9 million since 2005. Even still, more than half of millennial and Gen Z renters consider buying, with 18 percent seriously considering it.

Both lifestyles afford their fair share of pros and cons. So before you meet with a real estate agent, consider these five costs homeowners pay that renters don’t - they could make you reconsider buying altogether.

1. Property taxes

As long as you own a home, you’ll pay property taxes. The typical U.S. homeowner pays $2,110 per year in property taxes, meaning they’re a significant - and ongoing - chunk of your budget.

Factor this expense into the equation from the get-go to avoid surprises down the road. The property tax rates vary among states, so try a mortgage calculator to estimate costs in your area.

2. Homeowners insurance

Homeowners insurance protects you against losses and damage to your home caused by perils such as fires, storms or burglary. It also covers legal costs if someone is injured in your home or on your property.

Homeowners insurance is almost always required in order to get a home loan. It costs an average of $35 per month for every $100,000 of your home’s value.

If you intend to purchase a condo, you’ll need a condo insurance policy - separate from traditional homeowner’s insurance - which costs an average of $100 to $400 a year.

3. Maintenance and repairs

Don’t forget about those small repairs that you won’t be calling your landlord about anymore. Notice a tear in your window screen? Can’t get your toilet to stop running? What about those burned out light bulbs in your hallway? You get the idea.

Maintenance costs can add an additional $3,021 to the typical U.S. homeowner’s annual bill. Of course, this amount increases as your home ages.

And don’t forget about repairs. Conventional water heaters last about a decade, with a new one costing you between $500 to $1,500 on average. Air conditioning units don’t typically last much longer than 15 years, and an asphalt shingle roof won’t serve you too well after 20 years.

4. HOA fees

Sure, that monthly mortgage payment seems affordable, but don’t forget to take homeowners association (HOA) fees into account.

On average, HOA fees cost anywhere from $200 to $400 per month. They usually fund perks like your fitness center, neighborhood landscaping, community pool and other common areas.

Such amenities are usually covered as a renter, but when you own your home, you’re paying for these luxuries on top of your mortgage payment.

5. Utilities

When you’re renting, it’s common for your apartment or landlord to cover some costs. When you own your home, you’re in charge of covering it all - water, electric, gas, internet and cable.

While many factors determine how much you’ll pay for utilities - like the size of your home and the climate you live in - the typical U.S. homeowner pays $2,953 in utility costs every year.

Ultimately, renting might be more cost-effective in the end, depending on your lifestyle, location and financial situation. As long as you crunch the numbers and factor in these costs, you’ll make the right choice for your needs.

Related:

Originally published August 18, 2015. Statistics updated July 2018.


from Zillow Porchlight https://www.zillow.com/blog/homeowners-pay-renters-dont-181888/

Tuesday, July 10, 2018

HARP Now Extended Through 2016

Since it first launched in 2009, the Home Affordable Refinance Program (HARP) has helped 3.2 million borrowers across the country lower their monthly payments by refinancing at historically low interest rates. Friday, FHFA Director Melvin Watt announced this relief won’t be ending any time soon.

HARP will continue through the end of 2016, allowing homeowners who owe more than their homes are worth and regularly make mortgage payments to refinance. To help eligible borrowers take advantage of this program, Zillow remains the only marketplace supporting HARP and FHA Streamline refinances.

The FHFA has started a 10-day Twitter campaign using the hashtag #HARPfacts to help spread the word. They’re targeting Chicago first, where nearly 40,000 Chicago-area homeowners could save an average $189 per month or $2,300 a year with HARP.

Get answers to your HARP questions here.

Related:


from Zillow Porchlight https://www.zillow.com/blog/harp-now-extended-through-2016-175787/

Monday, July 2, 2018

What You Need to Know About the Fair Housing Act

If you’ve searched for a new place to live recently, you’ve likely seen the Equal Housing Opportunity logo (an equal sign inside a house) on a landlord’s, real estate agent’s or lender’s paperwork.

But the Fair Housing Act is more than just a logo. It’s a federal law designed to protect renters and buyers from discrimination.

Here are some key points to know about the Fair Housing Act when you’re searching for a place to live.

What is the Fair Housing Act?

Also known as the Civil Rights Act of 1968, the Fair Housing Act was signed into law by President Lyndon B. Johnson just days after the assassination of Martin Luther King Jr., who had championed the cause for many years.

The act prohibits housing discrimination based on race, color, religion, national origin, sex, disability and familial status (sex was added in 1974, and disability and familial status were added in 1988).

At the time the act was signed, overt housing discrimination was a huge problem throughout the country, including the attempted segregation of whole neighborhoods and the outright rejection of qualified renters based on race and other factors.

Today, much of the discrimination in the housing market is less obvious, but it’s still an unfortunate reality.

According to the National Fair Housing Alliance (NFHA), over 25,000 housing discrimination complaints were filed with the federal government and local and national fair housing agencies in 2017. Over half of the complaints were based on disability, followed by race at 20 percent.

But these numbers reflect only reported incidents. The NFHA estimates that over 4 million instances of housing discrimination occur annually, but many people don’t realize they’ve been discriminated against - or know what steps to take when it happens.

What does housing discrimination look like?

Most of the people you encounter in your home search, including real estate agents, sellers, landlords, property management companies and lenders, are bound to Fair Housing Act regulations and additional state and local laws, based on where you live or are looking to live.

Fair Housing Act violations can occur in all phases of buying and renting, including in advertising, while you search, throughout the application process, in financing or credit checks, and during eviction proceedings.

Here are a few examples of discrimination people in protected classes have encountered:

  • A real estate agent tries to “steer” a buyer away from a certain neighborhood
  • A landlord tries to avoid renting to someone by saying the unit advertised has been rented when it hasn’t
  • A property management company refuses to rent to a family with children or requires a higher deposit
  • A landlord evicts a person of color for a reason they wouldn’t evict a white tenant for
  • A mortgage broker asks questions or requests excessive documentation from an immigrant couple that they wouldn’t request from another buyer
  • A lender charges a single woman a higher interest rate than what her credit score should dictate
  • A landlord refuses to make reasonable accommodations for a tenant who is disabled

What do I do if I’ve been discriminated against?

If you’ve been discriminated against in any of the ways above, or if you suspect that other actions taken by a property manager, landlord, real estate agent, broker or lender may be discriminatory, there are many resources at your disposal.

  1. File a report: File a complaint with your regional Department of Housing and Urban Development (HUD) office - find yours at HUD.gov. You can also file a complaint on the national HUD website or with local housing resources found through the NFHA.
  2. Get more info from local housing agencies: You can find a list of local housing counselors at HUD.gov. Besides answering questions about discrimination claims, these agencies provide home buyer education workshops, pre-purchase counseling and rental housing assistance.
  3. Talk to an attorney: Like any other legal issue, when pursuing a complaint under the Fair Housing Act, it’s smart to consult a lawyer.
  4. Find people you can trust: If you experienced housing discrimination from your real estate agent, mortgage broker or lender, it’s time to find a new professional to help you in your home search. Ask friends, family members and colleagues for referrals they know, like and trust. Remember - these real estate professionals are working for you, so their only concern should be finding you the home that’s right for you.

Related:


from Zillow Porchlight https://www.zillow.com/blog/what-you-need-to-know-about-the-fair-housing-act-227310/

Friday, June 29, 2018

The Do's and Don'ts of Home Equity Loans

Home equity is a valued resource, and if you have it, you might be tempted to tap that wealth for other purposes. A home equity loan, which allows you to use your home’s equity as collateral, is a great way to do this. But depending on your personal situation, it may not be the right thing to do.

Here’s when a home equity loan makes sense - and when it doesn’t.

DON’T: Fund a lifestyle

Remember when homeowners yanked cash out of their homes to fund affluent lifestyles they couldn’t really afford? These reckless borrowers, with their boats, fancy cars, lavish vacations and other luxury items, paid the price when the housing bubble burst. Property values plunged, and they lost their homes.

Lesson learned: Don’t squander your equity! Look at a home equity loan as an investment - not as extra cash when making spending decisions.

DO: Make home improvements

The safest use of home equity funds is for home improvements that will add to the home’s value. If you have a one-time project (e.g., a new roof), then a home equity loan might make sense.

If you need money over time to fund ongoing home improvement projects, then a home equity line of credit (HELOC) would make more sense. HELOCs let you pay as you go and usually have a variable rate that’s tied to the prime rate, plus or minus some percentage.

DON’T: Pay for basic expenses or bills

This is a no-brainer, but it’s always worth reiterating: Basic expenses like groceries, clothing, utilities and phone bills should be a part of your household budget.

If your budget doesn’t cover these and you’re thinking of borrowing money to afford them, it’s time to rework your budget and cut some of the excess.

DO: Consolidate debt

Consolidating multiple balances, including your high-interest credit card debts, will make perfect sense when you run the numbers. Who doesn’t want to save potentially thousands of dollars in interest?

Debt consolidation will simplify your life, too, but beware: It only works if you have discipline. If you don’t, you’ll likely run all your balances back up again and end up in even worse shape.

DON’T: Finance college

If you have college-age children, this may seem like a great use of home equity. However, the potential consequences down the road could be significant. And risky.

Remember, tapping into your home equity may mean it takes longer to pay off the loan. It also may delay your retirement or put you even deeper in debt. And as you get older, it will likely be more difficult to earn the money to pay back the loan, so don’t jeopardize your financial security.

Related:

Note: The views and opinions expressed in this article are those of the author and do not necessarily reflect the opinion or position of Zillow.

Originally published February 23, 2016.


from Zillow Porchlight https://www.zillow.com/blog/dos-donts-of-home-equity-loans-192836/

Wednesday, April 18, 2018

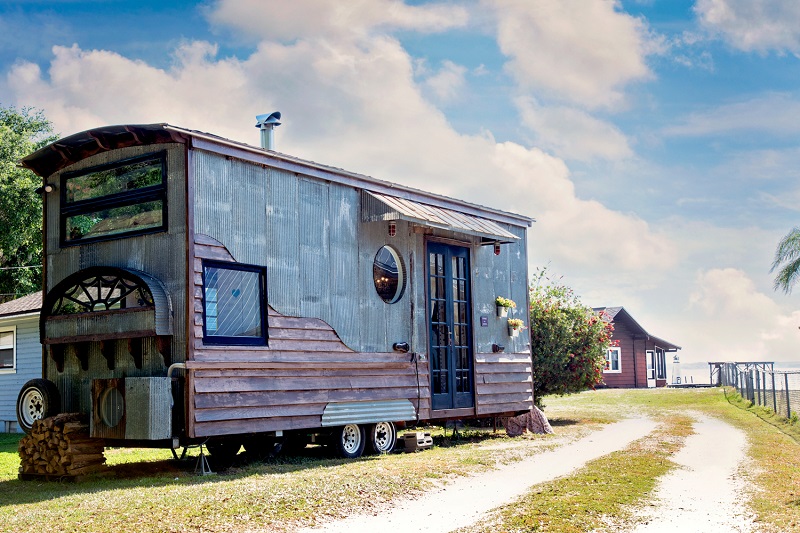
This Tiny Home Has Its Own Pizza Oven – House of the Week

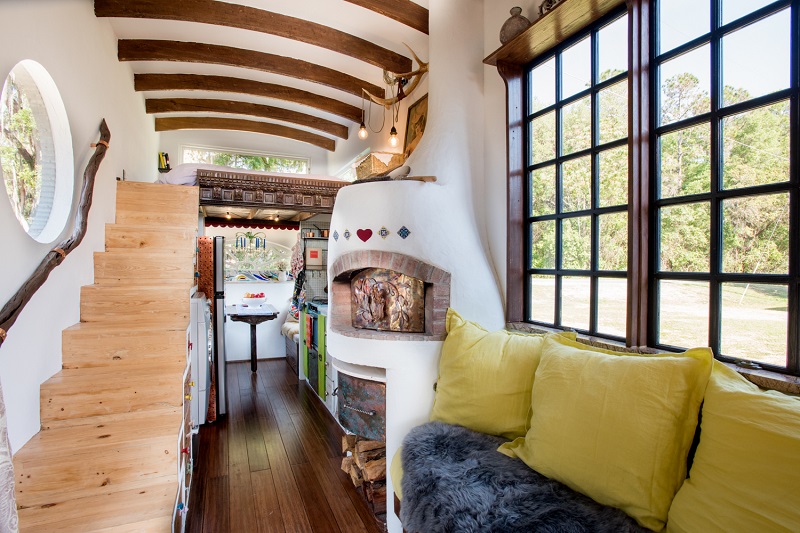
Forget waiting 45 minutes for the delivery guy to show up. In this custom tiny home, pizzas are ready in just two minutes!

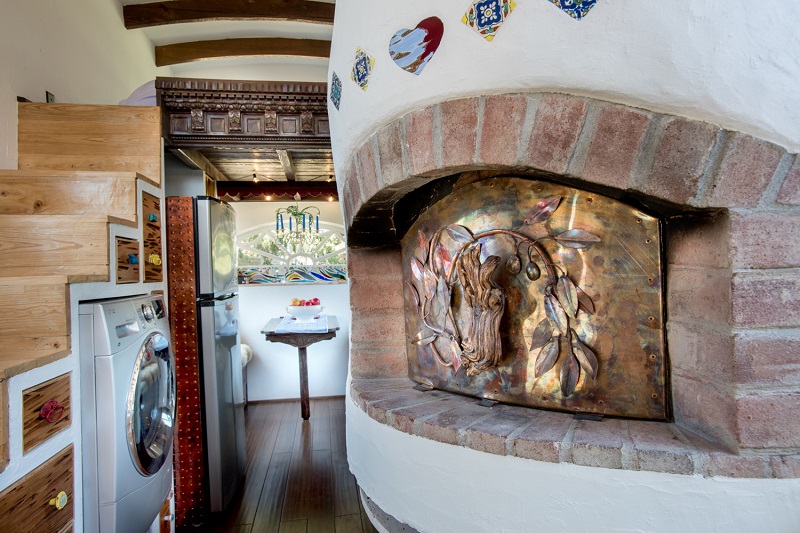
Empty nesters looking to avoid the burden of a big mortgage, Robert and Rebekah Sofia embarked on a 20-month journey designing and building a 221-square-foot home in Ocklawaha, FL. Most people would balk at the idea of putting a 800-degree wood-fired pizza oven in such a small space. But with layers of plaster, cement and a heavy metal door, it’s completely insulated.

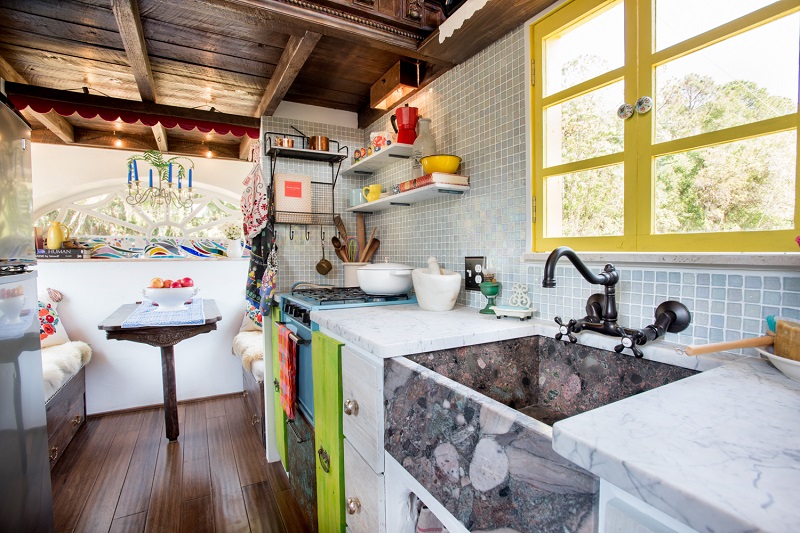
The Floridians were passionate about bringing a European flavor to their design and using recycled building materials. From the exterior corrugated metal to the cedar planks and doors - everything had a prior life. Best of all: The materials only cost $15,000.

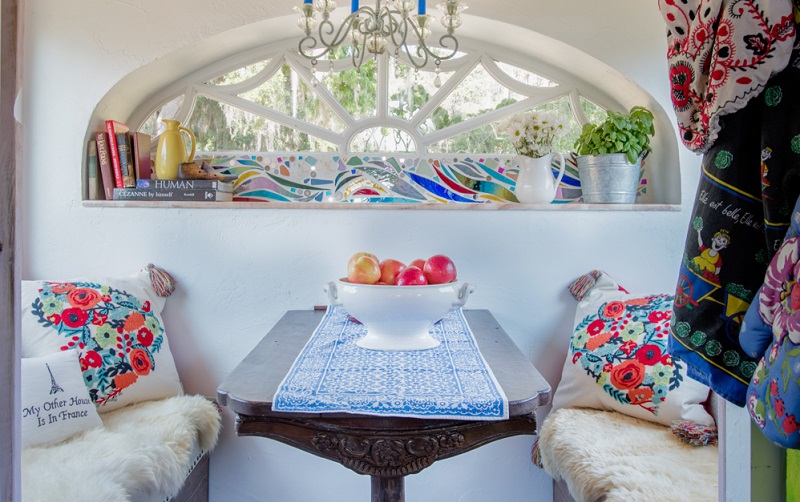
In addition to the pizza oven, there are amenities you might not expect in a tiny house: a big apron sink, outdoor soaking tub, formal dining room with a chandelier, a hangout music loft and his-and-hers closets.

Photos by John Jernigan.

Related:

The post This Tiny Home Has Its Own Pizza Oven – House of the Week appeared first on Zillow Porchlight.


from Zillow Porchlight https://www.zillow.com/blog/tiny-home-pizza-oven-226014/